Digitalization has brought formal credit closer to Filipinos long been failed by traditional financial infrastructure that was never built for them. But as the industry expands, access alone is no longer enough. True financial inclusion also requires consumers to have the information, flexibility, and control to make credit work for their lives.
For global credit infrastructure company Tala, that means looking beyond the availability of credit to the experience surrounding it: how borrowers are treated, how regulation responds to different models of lending, and how data can help financial institutions better understand people who remain difficult to assess through conventional systems. Together, these elements can support a safer and more sustainable digital lending ecosystem while giving more consumers meaningful financial agency.
Treating Borrowers With Dignity
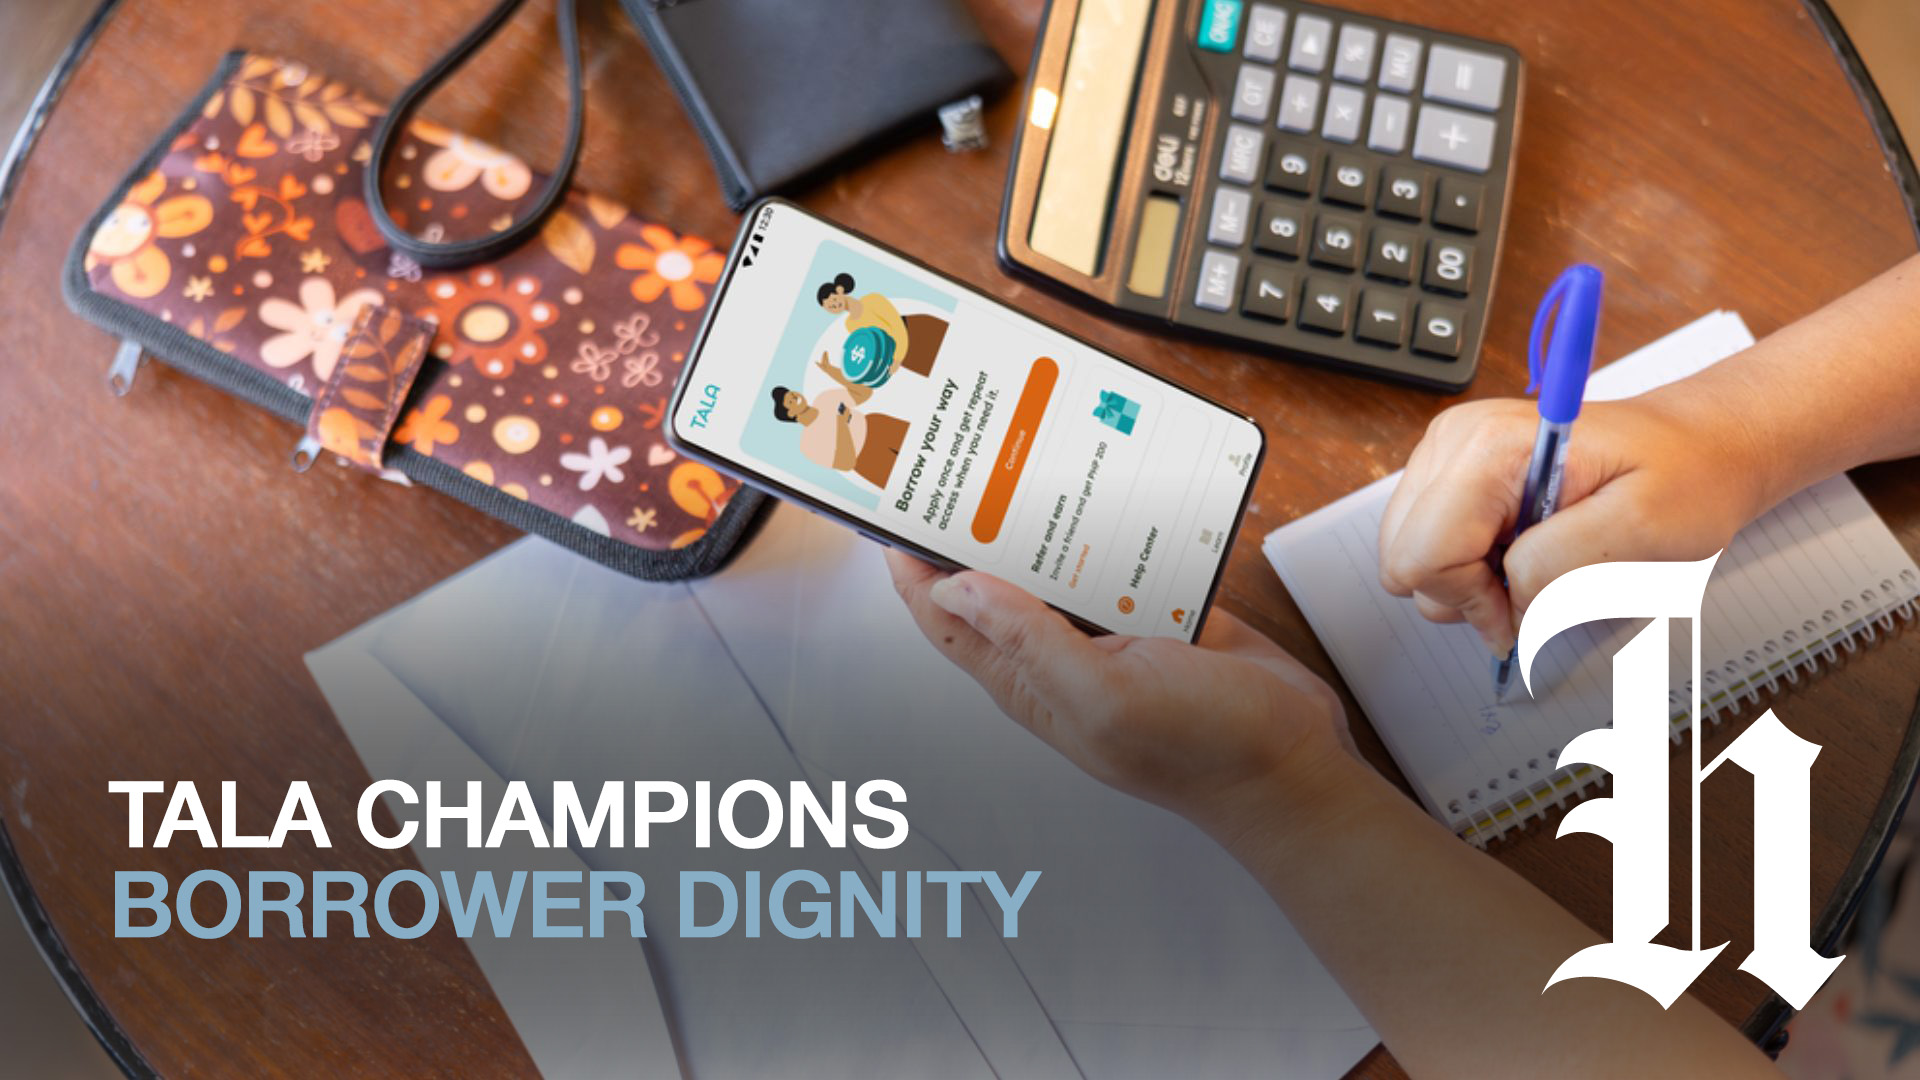
That starts with how customers are treated throughout the credit journey, particularly when circumstances make repayment difficult. “What we’ve realized for the last 10 years is that most customers typically have a willingness to pay back. It’s really about providing flexibility and the right tools and, of course, treating them with dignity, treating them fairly,” said Tala Philippines President and General Manager Moritz Gastl.
That belief is the foundation of Tala’s Debt with Dignity advocacy, developed from its Global Debt Collection with Dignity Initiative, which calls for fairness and respect throughout the credit experience, including during collections. When borrowers understand their obligations and are given appropriate tools and flexibility, they are better positioned to make informed decisions rather than lose control of their financial lives when circumstances change.
“Tala actively supports reforms and new regulations that solve consumers’ top problems. For example, to address unfair collection practices, we advocate for accreditation of debt collection agencies and publication of true, transparent information on financial products through our Debt with Dignity campaign. We recognize that pairing these structural changes with digital and financial literacy would strengthen responsible, sustainable economic participation and ultimately, drive capital market growth and innovation in the Philippines,” said Gastl Tala.
Tala also advocates for regulation that is risk-based and proportionate to the purpose, cost structure, and business model of different financial institutions, creating guardrails that protect consumers without closing off responsible approaches to reach people conventional systems continue to miss.
Using Data To Reach Overlooked Entrepreneurs
That challenge is particularly visible among nano and microentrepreneurs, many of whom run viable businesses without conventional collateral or extensive credit histories traditionally required by lenders. Gastl said 27% of Tala’s customers are nanoentrepreneurs, including sari-sari store owners using Tala credit as working capital to restock goods.
Reaching them requires a different approach to thin-file borrower underwriting. Tala combines behavioral, external, and telco data with proprietary models and real-time credit decisioning. Since its inception, Tala has created underwriting records across more than 50 million applicants giving it a view of credit risk beyond those who meet traditional approval thresholds.
That full-spectrum dataset underpins Tala InSight, which uses Tala’s risk intelligence to assess customers beyond a static credit score and tailor terms to their circumstances. Drawing on approved and declined applicants across markets and risk profiles allows its models to identify patterns traditional credit histories can overlook. This capability forms part of the broader Tala credit infrastructure for reaching consumers with limited formal financial records.
“Cash flow-based data and payment data haven’t gone away; they are incredibly important. But paired with behavioral data, device data, and telco data, we are in a unique position to target those nano-level entrepreneurs more so than existing financial institutions,” Gastl said.
Nine out of 10 borrowers who used Tala credit for business purposes reported an improved business outlook, citing greater stability, expansion, and confidence. Tala is extending that experience through partnerships with technology companies and ecosystems, bringing its risk intelligence and credit infrastructure to platforms seeking to reach more thin-file consumers.
For Tala, the opportunity ahead is not simply to extend more credit, but to make access more useful and responsive to the people it is intended to serve. By bringing together dignified lending, consumer-centric co-regulation, and data-driven decisioning, Tala is helping shape an industry where growth is measured not only by how many consumers it reaches, but by how well it enables them to move forward.